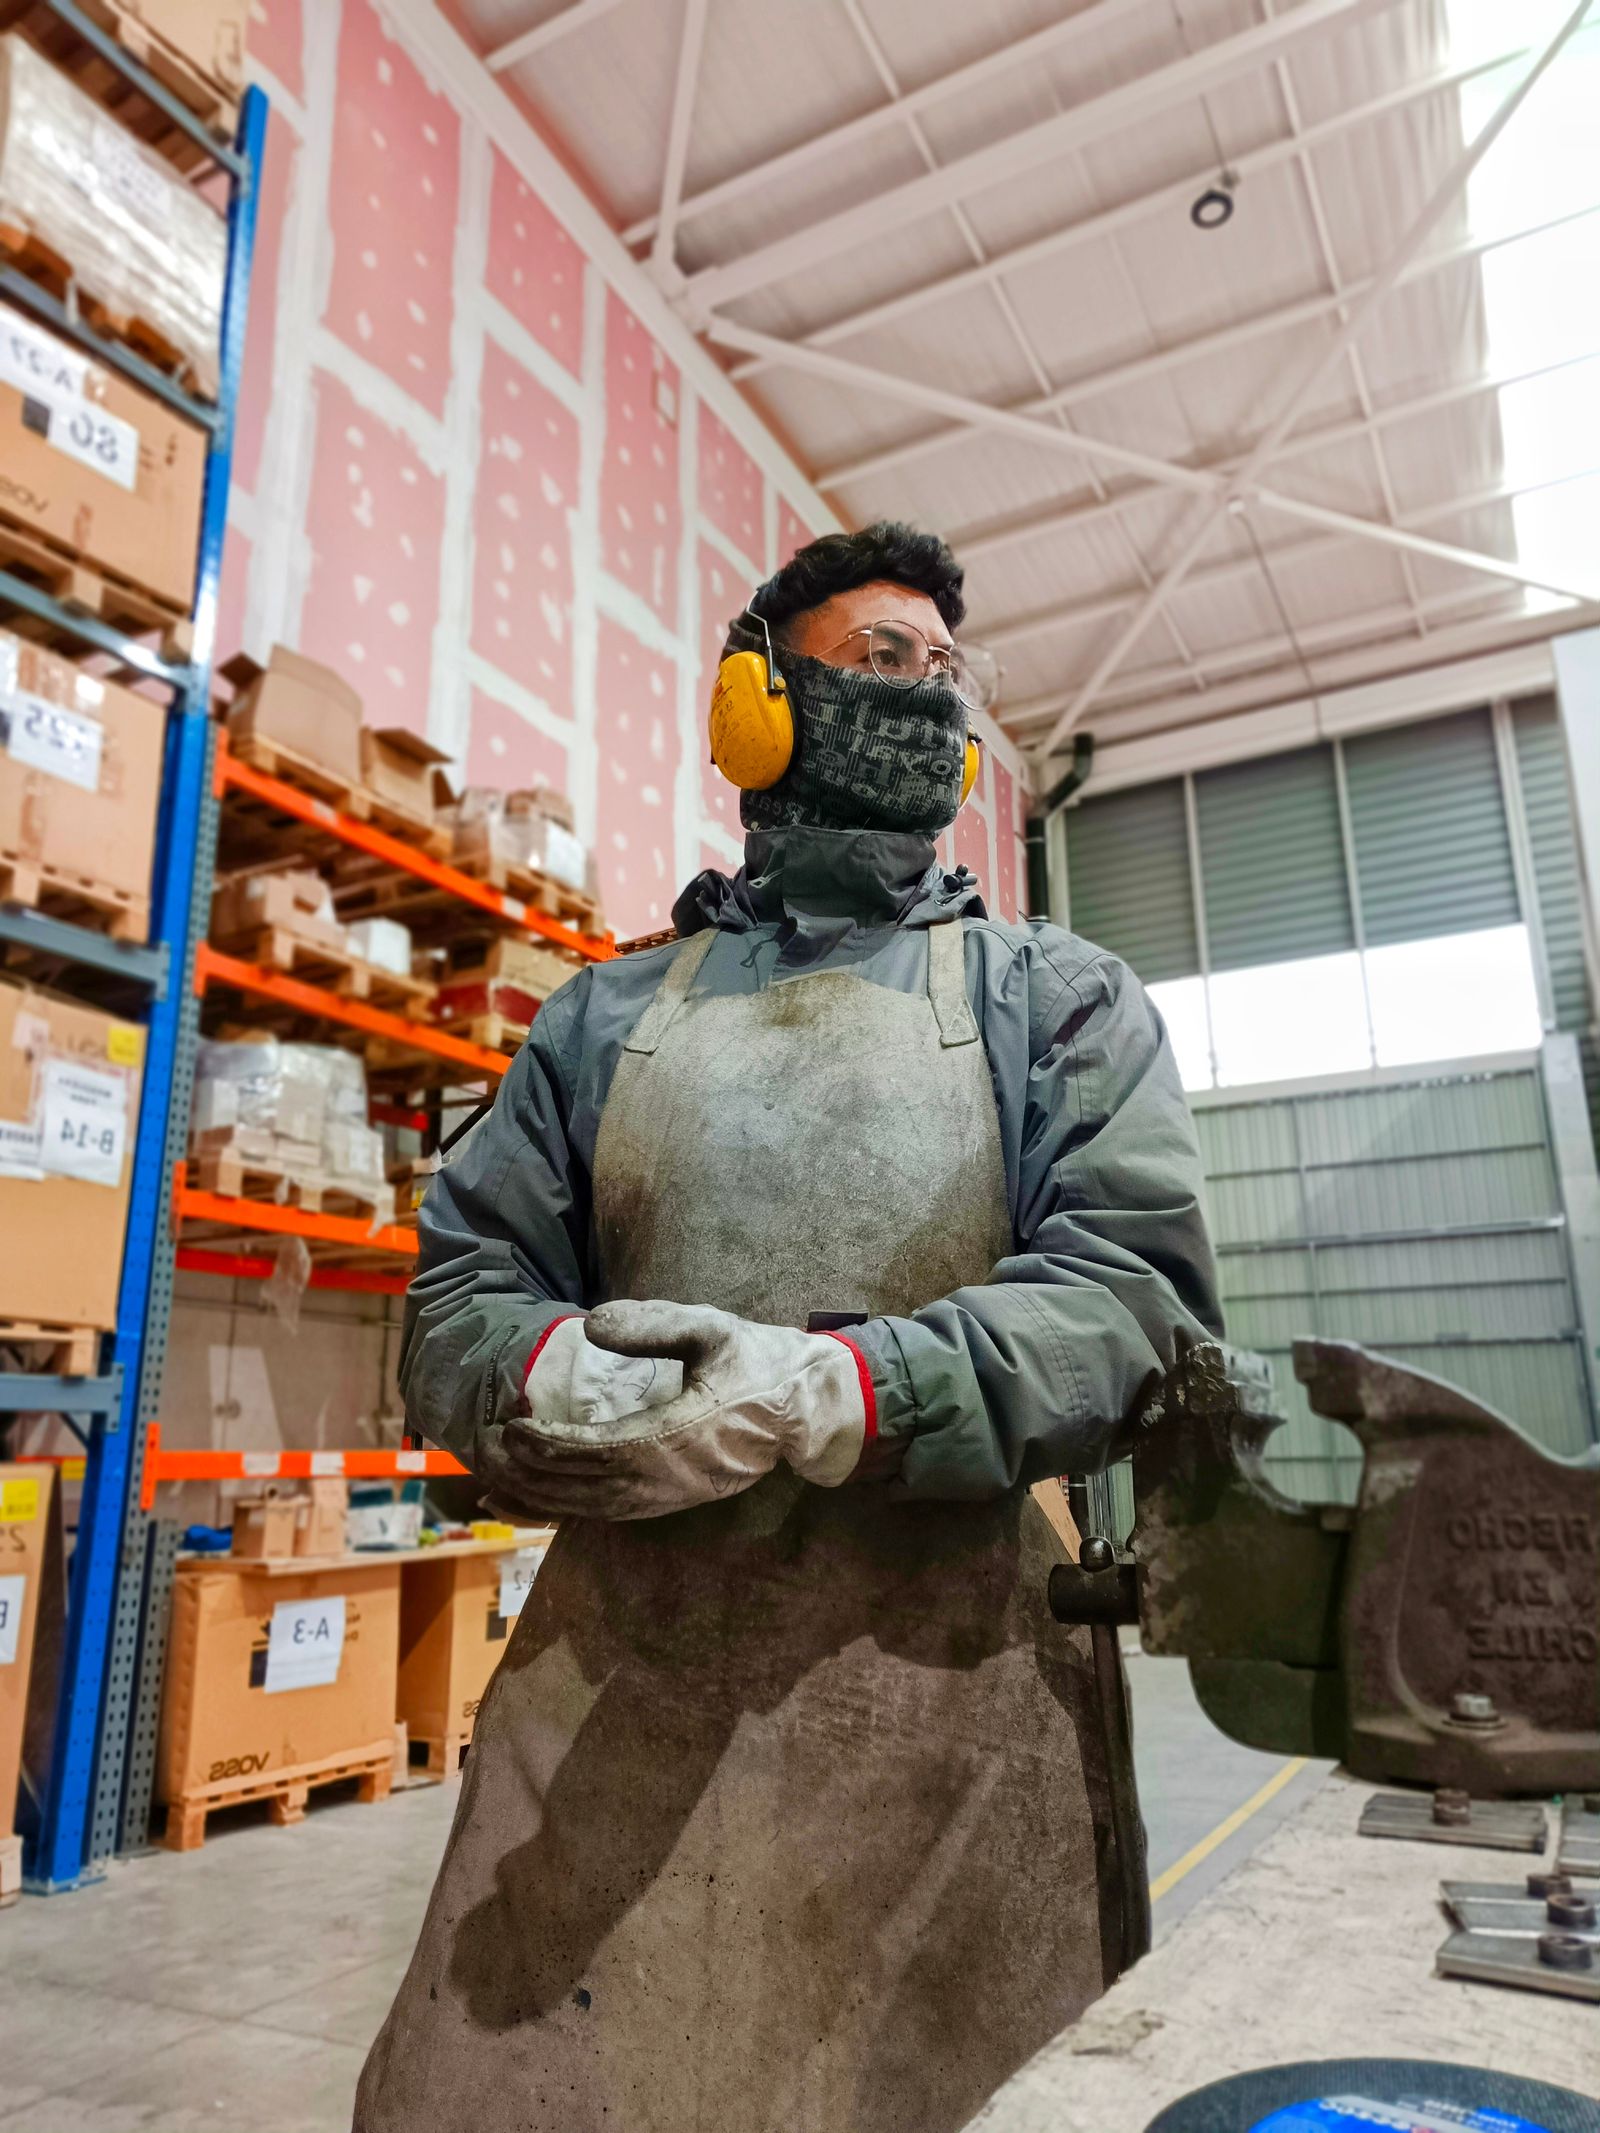
Warehouse & factory deductions at a glance
Generally, you need to have paid the expense yourself, it must directly relate to earning your employment income, and you need the required records. For mixed work and private use, only the work-related portion is generally deductible.
Who is this guide for?
This guide is for Nepali employees working in Australian warehouses, factories, manufacturing plants, packing facilities, production lines and distribution centres. Your deductions depend on your actual duties and expenses, not simply your job title.
1. Protective clothing and safety footwear
The ATO allows deductions for eligible protective clothing and footwear that protect you from specific risks of injury or illness associated with your work. Depending on your duties, this can include steel-capped boots, protective gloves, fire-resistant clothing, safety-coloured or hi-vis clothing and overalls where the relevant requirements are met.
2. Safety equipment and PPE
You may be able to claim safety equipment you purchase yourself for performing your duties. The ATO's factory-worker guidance includes goggles and breathing masks as examples. You cannot claim an item supplied by your employer or a cost that was reimbursed.
3. Ordinary clothing is generally not deductible
Conventional clothing such as ordinary jeans, shirts and sneakers is generally private even if your employer requires you to wear it or you only wear it at work. Eligible protective clothing and qualifying uniforms are different.
4. Laundry and cleaning
If the clothing itself qualifies as deductible work clothing, eligible cleaning, repair or maintenance costs may also be deductible. Washing ordinary private clothing does not make it deductible.
5. Tools and equipment
Tools or equipment you buy and use for your duties may be deductible. The ATO factory-worker guide gives examples such as an air compressor, drill or hammer. An item costing $300 or less may qualify for an immediate deduction if the conditions are satisfied. Items over $300 are generally claimed over time through decline in value. Sets and substantially identical items can affect this treatment.
Private use must be apportioned. You cannot claim tools supplied by your employer or another person.
6. Forklift licence and special licences
The initial cost of obtaining a special licence or certificate to gain employment — such as initially getting a forklift licence — is generally not deductible. However, the additional cost of renewing a special licence required for your current duties may be deductible. Your ordinary driver's licence and its renewal are generally private even if your employer requires you to hold it.
7. Union and professional association fees
Eligible union fees and relevant professional association fees can be deductible. Keep the statement or receipt showing what you personally paid.
8. Overtime meal expenses
Normal meals, drinks and snacks during ordinary working hours are generally private, even if you receive a general meal allowance. A specific rule can apply where you receive an overtime meal allowance under an industrial law, award or agreement, it is included in assessable income, and you buy and eat a meal while working overtime.
9. Car and travel expenses
Normal travel between home and your regular warehouse or factory is generally private. Some travel performed in the course of your duties, such as eligible travel directly between workplaces, can be treated differently.
10. Phone and internet
If you use your own phone or internet to perform employment duties, the eligible work-related portion may be deductible where you have appropriate records. Private use must be excluded.
11. Work-related training
Eligible self-education expenses can be deductible where they have the required connection with your current duties, such as maintaining or improving skills you already use. Training mainly undertaken to qualify for a new occupation or job can be treated differently.
Quick deduction comparison
| Expense | Possible treatment | Key point |
|---|---|---|
| Steel-capped safety boots | May be deductible | Must protect against a genuine work risk. |
| Gloves, goggles, breathing mask | May be deductible | Must be work-related and paid by you. |
| Ordinary jeans or sneakers | Generally not | Conventional clothing is private. |
| Work tools | May be deductible | Cost, private use and decline-in-value rules matter. |
| Initial forklift licence | Generally not | Initial cost to gain employment is not deductible. |
| Special licence renewal | May be deductible | Can qualify if needed for current duties. |
| Driver's licence | Generally not | Ordinary driver's licence costs are private. |
| Union fees | May be deductible | Keep evidence of payment. |
| Normal lunch | Generally not | Ordinary meals are private. |
| Eligible overtime meal | May be deductible | Specific allowance and overtime conditions apply. |
| Home to normal workplace | Generally not | Ordinary commuting is private. |
| Reimbursed expense | No | You cannot claim a cost reimbursed to you. |
Example: Nepali warehouse worker
Suppose Bikash works as a warehouse storeperson and forklift operator. He buys his own steel-capped boots and protective gloves to protect against workplace risks, pays to renew the special forklift licence needed for his existing duties, and pays annual union fees.
Depending on the detailed rules and his records, those costs may be deductible. Ordinary jeans, normal lunch, an ordinary driver's licence and daily travel from home to the same warehouse are generally private.
What if your employer pays an allowance?
Receiving an allowance does not automatically create a deduction for the same amount. Where an allowance is assessable, you still need to actually incur an eligible expense and satisfy the deduction and record-keeping rules.
What if your employer reimburses you?
If your employer fully reimburses an expense, you generally cannot also claim it as your own work-related deduction.
Records to keep
- receipts and invoices for protective gear, tools and other expenses
- records supporting the work percentage of mixed-use equipment
- evidence showing whether a licence payment was an initial cost or renewal
- payslips and income statements showing allowances
- travel records where an eligible work trip is claimed
- details of employer reimbursements.
Common mistakes to avoid
- claiming ordinary sneakers, jeans or conventional clothing
- claiming the initial cost of a forklift licence obtained to get a job
- claiming an ordinary driver's licence
- claiming every meal because you work long shifts
- claiming normal home-to-work travel
- claiming employer-supplied or reimbursed tools
- claiming 100% of mixed-use equipment
- assuming an allowance automatically equals a deduction
- failing to keep evidence.
Before lodging: worker checklist
- Check all employment income and assessable allowances.
- Separate protective clothing from ordinary clothing.
- Review tools and equipment you purchased yourself.
- Separate initial licence costs from eligible renewal costs.
- Check overtime meal claims against the specific rules.
- Exclude ordinary commuting.
- Remove reimbursed expenses.
- Apportion private use where required.
- Keep evidence for each deduction.
Frequently asked questions
Need help with your warehouse or factory worker tax return?
Hamro Accountant can help you review your income, allowances, records and eligible deductions.
General information only: This article is general Australian tax information and not personal tax, financial or legal advice. Deductibility depends on individual circumstances and the law applying to the relevant income year. Check current ATO guidance or obtain advice from a registered tax professional before lodging.